
Curious about how balance transfers can impact your credit score? Buckle up, because we’re about to dive into the nitty-gritty of this financial maneuver that can either make or break your credit standing. Picture this: you’ve transferred a chunk of debt from one credit card to another with a lower interest rate, hoping to save some cash in the long run. Sounds like a savvy move, right? But hold on a second – did you consider how this could sway your credit score in the grand scheme of things?
Balance transfers can be a double-edged sword when it comes to your credit score. On one hand, they could potentially boost your score by lowering your credit utilization ratio. On the flip side, they might also ding your score if you’re not careful with the process. So, before you make that next balance transfer, let’s unravel the mystery of how it could impact your credit score – and make sure you’re making a financially sound decision.
Benefits of Balance Transfers
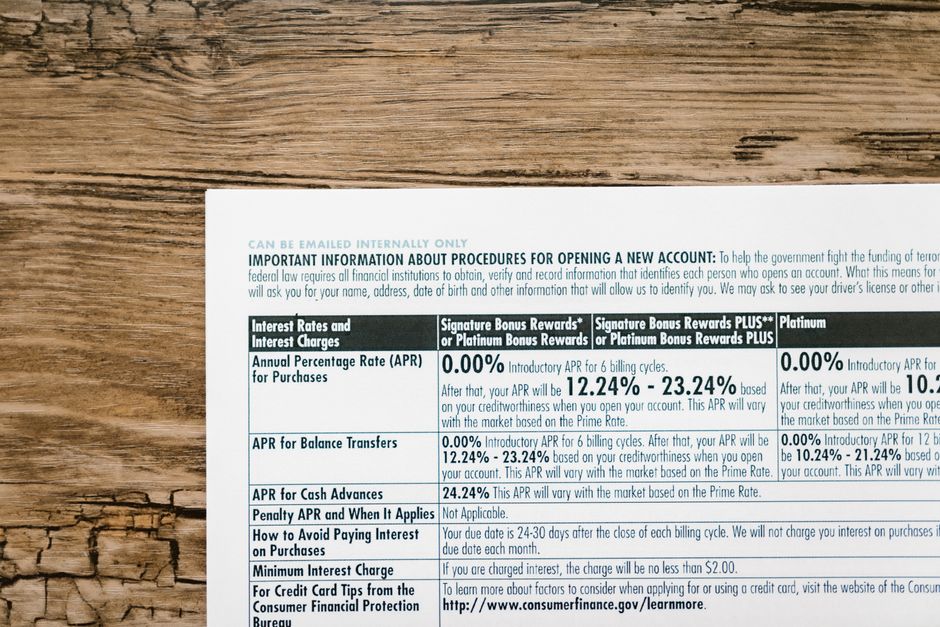
Balance transfers offer several advantages to individuals looking to manage their debt more effectively. One key benefit is the potential to save money on interest payments. By transferring high-interest debt to a new credit card with a lower or 0% introductory APR, individuals can reduce the amount of interest they pay each month, allowing them to pay off their debt faster.
Another benefit of balance transfers is the opportunity to consolidate multiple debts into one, simplifying the repayment process. This can help individuals stay organized and focused on their financial goals. Additionally, some credit card issuers offer rewards and incentives for balance transfers, such as cashback bonuses or points, providing further value to cardholders.
Risks of Balance Transfers
While balance transfers can be advantageous, they also come with certain risks that individuals should be aware of. One potential risk is incurring balance transfer fees, which are typically calculated as a percentage of the amount transferred. These fees can offset the savings gained from a lower APR, especially for individuals transferring a large balance.
Another risk to consider is the temptation to continue accumulating debt on the original card after transferring the balance. This can lead to a situation where individuals have multiple sources of debt to manage, potentially exacerbating their financial difficulties. Additionally, missing payments or not adhering to the terms of the balance transfer offer can result in penalty fees or a higher interest rate, negating the initial benefits of the transfer.
 How Balance Transfers Affect Your Credit Score
Risks of Balance Transfers
High Fees: One of the primary risks associated with balance transfers is the potential for high fees. Many credit card companies charge a balance transfer fee, typically around 3% to 5% of the transferred amount. These fees can add up quickly, especially if you are transferring a large balance. It’s crucial to factor in these fees when considering a balance transfer to ensure that the overall savings outweigh the costs.
Potential for Increased Debt: Another risk of balance transfers is the temptation to accumulate more debt. When you transfer a balance to a new credit card with a lower interest rate, it can be tempting to continue using the old card or to start using the new card for additional purchases. This can result in a higher overall debt load, making it more challenging to pay off balances in the long run. It’s essential to exercise discipline and avoid using credit cards for unnecessary purchases to prevent falling deeper into debt.
Steps to Perform a Balance Transfer
Step 1: Choose the Right Balance Transfer Card
Research and compare different credit card offers to find one with a low or 0% introductory APR on balance transfers. Look for a card with favorable terms and conditions that suit your financial situation.
Step 2: Gather Necessary Information
Collect all the details of the debt you want to transfer, including the account number, current balance, and payment address. You will also need the new credit card information, such as the card number and issuer’s contact details.
Step 3: Apply for the New Credit Card
Submit an application for the chosen balance transfer card. Provide accurate information and ensure that you meet the issuer’s eligibility criteria. Upon approval, you will receive the new card in the mail.
Step 4: Initiate the Balance Transfer
Contact the new credit card issuer to request the balance transfer. You may be able to do this online, over the phone, or through a balance transfer form provided by the issuer. Provide the necessary details of the debt you wish to transfer.
How Balance Transfers Impact Credit Scores
Credit Score Impact: Balance transfers can have both positive and negative impacts on credit scores. When you transfer a balance to a new card with a lower interest rate, it can help improve your credit utilization ratio, which is the amount of credit you are using compared to the total available credit. A lower utilization ratio typically results in a higher credit score. However, opening a new credit account for the balance transfer can temporarily lower your average account age, which may have a slight negative impact.
Hard Inquiries: Applying for a new credit card to facilitate a balance transfer usually results in a hard inquiry on your credit report. While a single hard inquiry may only have a minor impact on your credit score, multiple inquiries within a short period can signal to lenders that you are taking on too much debt, potentially lowering your score. It’s essential to be mindful of the number of credit inquiries you make when considering a balance transfer to minimize any negative effects on your credit score.
Tips for Using Balance Transfers Wisely
Plan Ahead: Before initiating a balance transfer, create a detailed plan to pay off the transferred balance within the promotional period. Be mindful of the transfer fee and interest rate after the promotional period ends.
Avoid New Charges: Refrain from making new purchases on the credit card used for the balance transfer. Focus on clearing the transferred balance to fully benefit from the lower or 0% interest rate.
Monitor Promotional Period: Keep track of the promotional period’s end date to avoid unexpected interest charges. Set reminders or alerts to ensure timely repayment.
Compare Offers: Research and compare balance transfer offers from different credit card issuers. Look for low or 0% introductory APR, longer promotional periods, and minimal transfer fees to maximize savings.