
Imagine having the opportunity to improve your credit score while also building your savings. That’s the magic of a credit builder loan. This unique financial tool is designed to help individuals establish or improve their credit history in a safe and effective way. By making on-time monthly payments, you not only boost your credit score but also set aside money for your future financial goals. It’s like hitting two birds with one stone – securing your financial future while enhancing your creditworthiness. So, if you’re looking to strengthen your credit profile and enhance your financial well-being, a credit builder loan might just be the perfect solution for you.
How Does a Credit Builder Loan Work?
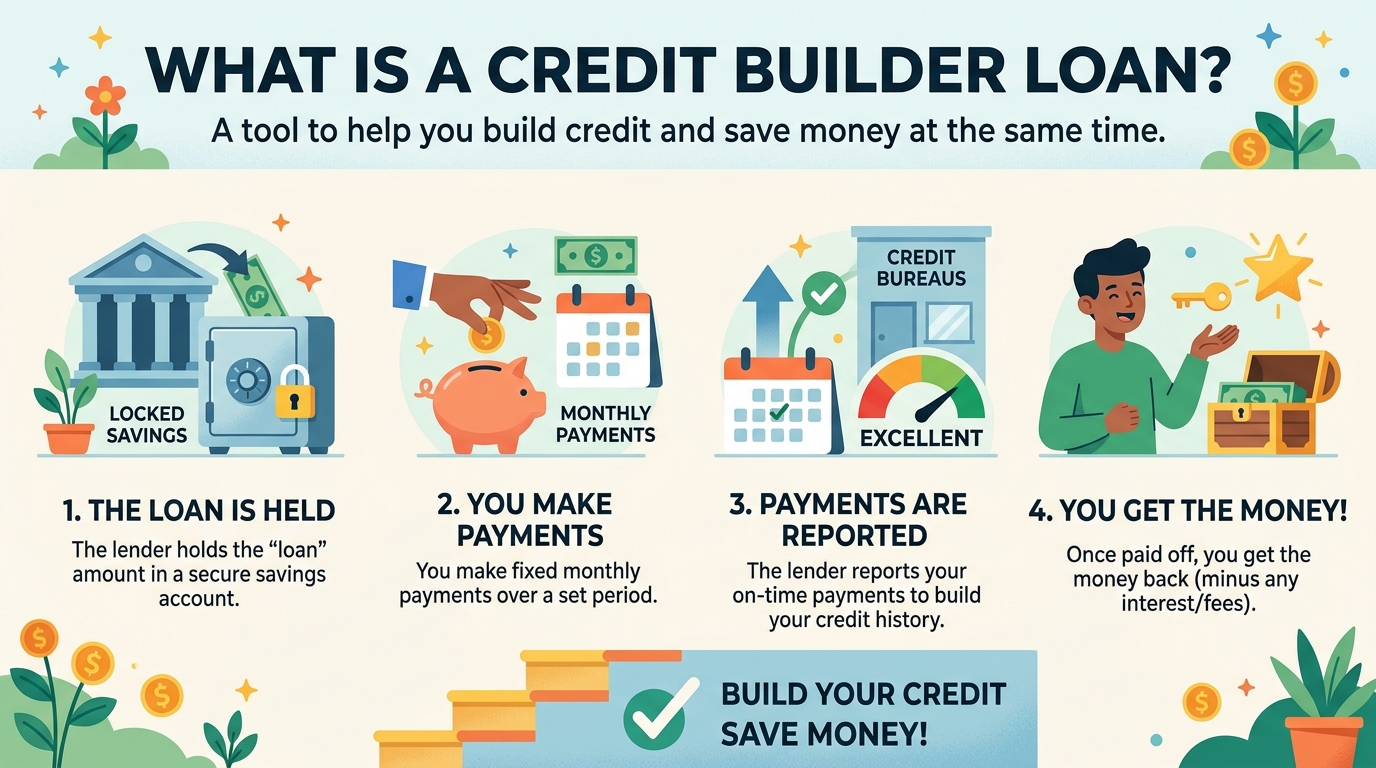
A credit builder loan is a unique financial product designed to help individuals establish or improve their credit scores. Unlike traditional loans, the primary purpose of a credit builder loan is not to provide immediate funds but to build credit history. When you take out a credit builder loan, the lender holds the loan amount in a savings account or certificate of deposit (CD) as collateral.
Each month, you make payments toward the loan, and these payments are reported to the credit bureaus. As you make timely payments, your credit score can gradually increase. Once you have repaid the loan in full, you receive the funds along with a potentially higher credit score. Overall, a credit builder loan serves as a tool to demonstrate responsible credit behavior and establish a positive credit history.
 What Is a Credit Builder Loan?
Who Can Benefit from a Credit Builder Loan?
Young Adults: Young adults who are new to credit or have limited credit history can benefit from a credit builder loan. By making on-time payments, they can establish a positive credit history and improve their credit score over time. This can help them qualify for better interest rates on future loans and credit cards.
Individuals with Poor Credit: Individuals with poor credit scores can also benefit from a credit builder loan. By responsibly managing the loan and making timely payments, they can gradually rebuild their creditworthiness. This can open up opportunities for them to access more affordable credit products in the future.
Tips for Choosing a Credit Builder Loan
Interest Rates: When choosing a credit builder loan, one important factor to consider is the interest rate. Look for a loan with a competitive interest rate that you can afford. Lower interest rates can save you money in the long run.
Loan Terms: Pay attention to the loan terms, including the repayment period and any fees associated with the loan. Make sure the terms align with your financial goals and capabilities. Longer repayment periods may result in lower monthly payments but could also mean paying more in interest over time.
Risks and Considerations
Interest Rates: One of the main risks associated with a credit builder loan is the high-interest rate that lenders may charge. Since these loans are designed for individuals with poor or no credit history, lenders often offset the risk by charging higher interest rates. Borrowers need to carefully consider whether they can afford the monthly payments before committing to a credit builder loan.
Impact on Credit Score: While a credit builder loan can help improve your credit score over time, missing payments or defaulting on the loan can have a negative impact. It’s crucial to make timely payments to avoid damaging your credit further. Additionally, some lenders may not report payments to all three major credit bureaus, which could limit the positive impact on your credit score.
In conclusion, a credit builder loan can be a valuable tool for individuals looking to establish or improve their credit history. By making regular, on-time payments, borrowers can demonstrate their creditworthiness to lenders and potentially qualify for better loan terms in the future. Additionally, the disciplined repayment structure of a credit builder loan can help individuals develop healthier financial habits and improve their overall financial well-being.
It is important to remember that while a credit builder loan can be beneficial, it is not a one-size-fits-all solution. Before committing to a credit builder loan, individuals should carefully consider their financial situation, goals, and ability to make consistent payments. It is also essential to shop around and compare different loan offers to ensure that the terms and conditions are favorable. Ultimately, with responsible use and careful planning, a credit builder loan can be a stepping stone towards a stronger financial future.